RiskGraph Institutional Data
Derived information signals extracted from consolidated, reconciled event probabilities for financial research and backtesting.
Product detailsCalibraSignal is building RiskGraphAI, the bridge between changing event probabilities and the financial assets they affect.
We consolidate event probabilities from multiple sources and use quantitative methodology to extract information signals, especially from probability jumps. AI connects those events to risks and assets; quantitative and ML prediction models estimate potential financial-market outcomes.
Research models & demos developed · Production services in development
Policy decisions · Geopolitics · Supply disruptions
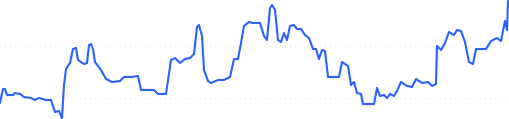
Sudden probability repricing · Illustrative data
Multi-source probability consolidation
Quantitative signal extraction
AI event–risk–asset graph
Quantitative & ML prediction models
Derived asset-level signals & event-risk monitoring
For institutions that want to use prediction-market information in financial research, portfolio monitoring and trading-platform workflows.
Derived information signals extracted from consolidated, reconciled event probabilities for financial research and backtesting.
Product detailsAI event–risk–asset mapping and quantitative models that study how probability changes relate to financial-market outcomes.
Product detailsEvent-risk context designed for broker and trading-platform workflows, including alerts, reports and asset-specific monitoring.
Product detailsThese product lines describe our development direction. Research models, a pipeline framework and broker demos exist; commercial production delivery is not yet live.
The same real-world event can appear in multiple prediction markets with different contract wording, resolution criteria and observation quality. We reconcile equivalent events and consolidate their probability information into a consistent research foundation.
Our quantitative methodology extracts information from probability repricing, with particular attention to material jumps. Quality checks help distinguish informative changes from stale prices and anomalous ticks. The intended deliverable is derived information signals and research features, rather than raw prediction-market feeds.
Explore our signal-extraction approachCombine probability information from multiple sources and match equivalent events.
Use quantitative methodology to identify informative probability changes and jumps.
Use derived features in asset- and horizon-specific quantitative and ML prediction models.
We combine event-to-asset reasoning, learned financial-market relationships and institutional workflow knowledge to turn probability repricing into researchable intelligence.
Our AI graph approach connects real-world events to the risks and probabilities they affect, then to relevant assets and exposures. It is designed to capture cross-market relationships and indirect transmission paths, rather than rely on a fixed event-to-asset lookup.
Our models learn how sudden probability jumps relate to subsequent financial-market moves. Asset- and horizon-specific research separates what has already moved in prices from what may still lie ahead, supported by walk-forward out-of-sample evaluation.
Front-office quantitative trading, cross-asset analytics and production engineering experience shape our product design. The outputs are designed around how research teams validate a new feature and how investment desks and brokers use event-risk intelligence.
Strong orthogonality to five standard price-based features across most tested asset/horizon combinations suggests information complementary to conventional financial signals.
In-sample research identifies cases where RiskGraph adds forward-return information after those standard features are included. This is a separate test from out-of-sample prediction.
Selected asset/horizon directional-prediction tests show statistically significant walk-forward out-of-sample results, with evaluation on held-out data.
Statistical significance is specific to selected out-of-sample tests; findings vary by asset and horizon, and weaker and null results also occur. This is historical research evidence, not live trading performance or a guarantee of future results.
Derived probability-change signals and asset-level features for research, modelling and backtesting.
Event-risk context, linked financial exposures and asset-specific analysis for investment decision support.
Planned embedded alerts, morning reports and risk panels for client-facing trading workflows.
Request a free trial of our derived data and signals, arrange a demo, and discuss asset coverage or quantitative evaluation with us.
Free trial & discuss